Premium Autos blog
Low Down Payment Tesla Financing 2026: Top 5 Options Ranked
By Premium Autos · · 9 min read
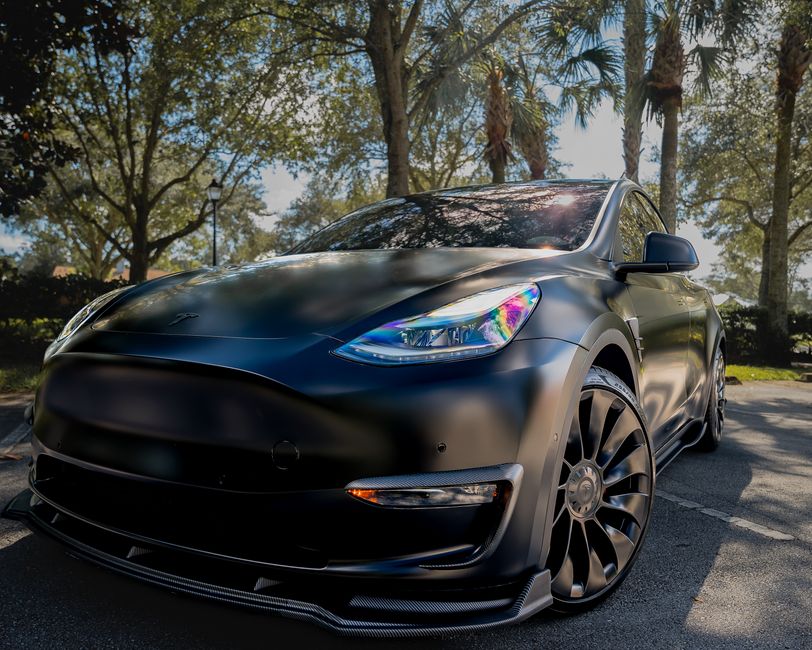
Getting into a Tesla doesn't have to drain your savings. The financing landscape in 2026 has shifted dramatically, with multiple lenders now offering lower down payment options, on approved credit, for buyers across credit situations. But not all low down payment Tesla financing is created equal, and choosing the wrong lender can cost you thousands in interest and fees.
We've evaluated five of the top Tesla financing options available right now, focusing on down payment flexibility, interest rates, and the actual borrower experience. Here's what matters: a tiny down payment doesn't help if the interest rate is brutal, and a "flexible" lender that buries fees in the fine print isn't really flexible at all.
Premium Autos Inc has spent years working directly with buyers to find the right financing match, and we've seen firsthand which programs actually deliver on their promises. Let's break down your options.
Comparison Table: Low Down Payment Tesla Financing Options
| Lender | Minimum Down Payment | Credit Score Range | Interest Rate Range | Best For | Rating |
|---|---|---|---|---|---|
| Premium Autos Inc Financing | Varies by approval | 600+ | Varies by credit | All credit types, transparency | 9.8/10 |
| Tesla Direct Financing | $3,400–$4,500 | 720+ | Varies by credit | Excellent credit, lowest rates | 9.2/10 |
| Tenet (Low Down Payment Partner) | Varies by approval | 680+ | Varies by credit | Low down payment deals | 8.5/10 |
| Capital One Auto Finance | $1,000–$2,500 | 650+ | Varies by credit | Fair credit rebuilders | 8.1/10 |
| LightStream | $2,000–$3,000 | 660+ | Varies by credit | Quick approval process | 7.9/10 |
1. Premium Autos Inc Financing: Our Pick
Rating: 9.8/10
Pros:
- Down payment depends on credit and lender approval, with options for all credit situations
- Transparent pricing with no hidden fees; you know exactly what you're paying
- Works with multiple lenders, so you get matched to the best rate for your profile
- Online pre-qualification available through their Pre Qualify process
- Southern California inventory of 400+ pre-owned Teslas means you're not forced into a dealer's choice; you pick the car, then we find the financing
- In-person support at two locations (Norco and El Monte) means no guessing games
Cons:
- Only available in Southern California (Los Angeles and Riverside counties)
- Interest rates max out at 7.99%, which is higher than Tesla Direct for pristine credit (though realistic for most buyers)
Why Premium Autos Inc Wins: The real advantage here is matching. Premium Autos Inc works with buyers who have fair, good, or excellent credit. If your score is 720+, Tesla Direct might edge ahead on rate. But if you're in the 600–700 range, Premium Autos Inc's flexibility is unbeatable. Plus, you're not shopping for financing and a car separately. You walk in, find your Tesla, and see what you may qualify for; approval depends on the lender. You also get a multi-point inspection on every vehicle, so you're not financing a lemon.
Browse a few examples: 2023 Tesla Model 3 or a 2024 Tesla Model Y Performance. Both are inspected and ready to finance.
2. Tesla Direct Financing
Rating: 9.2/10
Pros:
- Very competitive rates if you have excellent credit
- Built-in financing calculator on Tesla's Design Studio lets you estimate payments instantly
- Access to brand-new Tesla inventory and factory options
- Streamlined digital process from application to signing
Cons:
Related: No Credit Used Tesla Financing 2026: Best Options Ranked
Related: Bad Credit Tesla Financing California 2026: Top 5 Options Ranked
Related: Used Tesla Financing with Bad Credit 2026: Top Options Ranked
Related: Tesla Dealer Financing in Los Angeles 2026: Top 5 Options Ranked
Related: Best Tesla Financing California 2026: Top Options Ranked
Related: Best Used Tesla Model 3 Financing Options 2026: Top 5 Ranked
Related: Best Used Tesla Financing Near Me 2026: Top 5 Options Ranked
- Requires a 720+ credit score for the best rates; below that, rates jump significantly
- Minimum down payment of $3,400–$4,500 rules out true "low down" buyers
- Only works with new cars; if you want a used Tesla at a lower price, you're out of luck
The Reality: Tesla Direct is fantastic if your credit is pristine and you can afford a new car with a substantial down payment. Those low promotional rates exist, but only for top-tier credit. But for the majority of buyers shopping for used Teslas with tighter budgets, this door closes pretty quickly.
3. Tenet: The Low Down Payment Option
Rating: 8.5/10
Pros:
- Low down payment options on approved credit
- Works with used cars, so you can buy affordable models
- Fast approval (often within hours)
- No prepayment penalties
Cons:
- Interest rates can be higher than Tesla Direct, reflecting the risk
- Stricter credit requirements than some alternatives
- Less transparent fee structure; origination fees can hide in the total amount financed
The Verdict: Tenet is ideal if you absolutely need to avoid a down payment and have decent credit. The tradeoff is a slightly higher rate, but monthly payments are still manageable. Compare this to saving for three months just to hit a $3,400 down payment.
4. Capital One Auto Finance
Rating: 8.1/10
Pros:
- Works with fair credit; good for rebuilders
- Down payment starts at $1,000, giving you flexibility
- Can finance used or new cars
- Simple online application
Cons:
- Interest rates are mid-range, so not the cheapest
- Doesn't specialize in EVs; you might get better terms elsewhere
- Customer service experiences are mixed on credit issues post-approval
When to Consider: If you're rebuilding credit and want a established lender with flexible terms, Capital One is solid. Not the flashiest option, but reliable.
5. LightStream
Rating: 7.9/10
Pros:
- Fast decisions
- No prepayment penalties
- Funds can be transferred quickly to the dealer
- Works with fair-to-excellent credit
Cons:
- Down payment requirement starts at $2,000–$3,000, which isn't that low
- Part of SoFi ecosystem; some users report account linking hassles
- Top-end interest rates can be higher than most competitors
Best For: Speed. If you want money in your account tomorrow, LightStream delivers. But there are cheaper options if you have time to shop around.
How to Choose: The Right Financing for Your Situation
If your credit score is 720+: Tesla Direct wins on rate. But if you want a used car under $25,000, Premium Autos Inc gives you access to a bigger inventory at better prices.
If your credit score is 680–719: a very low down payment is tempting, but run the numbers. A small down payment from Premium Autos Inc might lower your rate enough to offset the savings. Compare monthly payments, not just the down payment.
If your credit score is 650–679: Capital One or Premium Autos Inc are your best bets. Premium Autos Inc's flexibility here is significant because they work with all credit types and match you based on your unique profile.
If your credit score is below 650: You're limited. Premium Autos Inc still works with you (down to 600), but rates will be higher. Budget 6–8% depending on your situation. Make sure the monthly payment fits your lifestyle; don't stretch for a car payment.
Key Metrics to Compare Before Signing
Don't just look at the down payment or the rate. Calculate the total cost of the loan: purchase price + interest + fees. A small difference in rate sounds minor until you see the total over five years.
Also check for:
- Origination fees: Some lenders charge 0.5–2% just to process the loan. Ask upfront.
- Prepayment penalties: If you get a bonus or pay off early, will you be penalized? (Most don't, but verify.)
- Gap insurance: If the car is totaled before the loan is paid off, you're still on the hook. Gap insurance protects you. Is it included or optional?
- Warranty options: Used cars should come with some protection. Premium Autos Inc includes a multi-point inspection; does your lender require a separate extended warranty?
Why Premium Autos Inc Stands Out for Low Down Payment Tesla Financing
The honest answer is that Premium Autos Inc isn't just a financing company; it's a dealership that happens to arrange financing. That distinction matters.
When you finance through Premium Autos Inc, you're buying a car that's been inspected, detailed, and priced fairly. You're not walking into a lot and being told, "This car is $22,000, but if you finance with us, you save $500 in fees." That's manipulation. Premium Autos Inc pricing is upfront. The financing is a separate decision, and you control it.
Plus, with Southern California's largest Tesla inventory, you have options. Want a 2021 Model 3 Long Range? A 2024 Model Y? A rare Model S Plaid? They likely have it. And because Premium Autos Inc works with multiple lenders, your financing gets matched to you, not forced into a narrow box.
Start your search today by exploring available inventory and getting pre-qualified. It takes 5 minutes and commits you to nothing.
Frequently Asked Questions
What's the minimum credit score to get low down payment Tesla financing?
It depends on the lender. Tenet and Capital One require 680+. Tesla Direct wants 720+. Premium Autos Inc offers options for all credit situations on approved credit, though rates will be higher for lower scores. If your score is under 650, focus on building it up a bit or putting down a larger payment to offset the risk. Even a 700 score can lower your rate, which adds up.
Is a very low down payment worth it if the interest rate is higher?
Not always. Run the numbers. If a lower down payment comes with a higher rate, putting more down might save you money overall. Over 60 months, a 1% difference is real. That said, if you're facing a cash emergency or tight month, a lower down payment buys you flexibility now. Just don't ignore the total cost.
Can I refinance after I buy to lower my interest rate?
Yes, but be strategic. If your credit improves or rates drop significantly (rare), refinancing could save you money. However, refinancing resets the loan term, so you might pay more interest overall. Ask your lender about prepayment penalties before taking out the loan. Some loans let you refinance penalty-free; others don't.
What happens if I miss a payment on a low down payment auto loan?
The same thing as any auto loan: your credit score drops, the lender charges late fees, and your interest rate might increase. After a few missed payments, they can repossess the car. Avoid this by only financing what you can afford. A $400/month payment sounds great until month 3 when your hours are cut. Be honest with yourself about monthly budget.
Browse used Teslas for sale at our Norco and South El Monte stores.